
What is debt consolidation?
Debt consolidation combines multiple debts into one new loan or account. It can simplify payments, but the money is still owed. The new account has its own costs and repayment terms.
What could be the benefit?
One payment may be easier to track. A lower rate could reduce interest costs, if you qualify. The benefit depends on the offer, fees and how long repayment takes.
A smaller payment can cost more overall
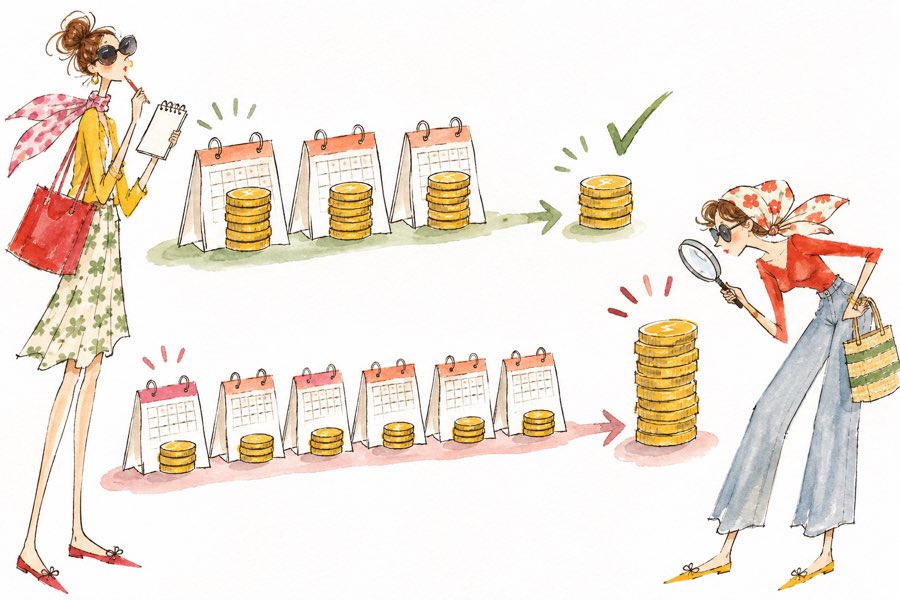
A lower monthly payment may come from a longer repayment period. That can increase total interest. Compare the full repayment cost, not just the amount due each month.
Which terms should you compare?
Review the annual percentage rate, fees, repayment length and total amount payable. Promotional rates may end. Consolidation is different from debt settlement, which tries to negotiate what creditors accept.
What should your plan include?
Check that the new payment fits your budget. Compare alternatives, such as a creditor payment plan or nonprofit credit counseling. Avoid building new balances on accounts you have just paid off.
You’ve finished the debt consolidation guide
Create your FREE account
Answer a few questions, then finish signing up to explore resources for your needs.
Continue →